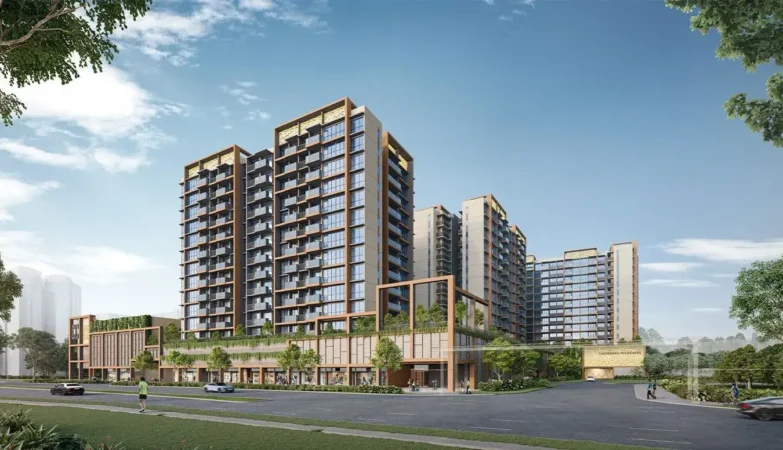
Executive Condominiums (ECs) occupy an exceptional tier in Singapore’s residential landscape. Designed to bridge the affordability gap between public subsidised housing and private developments, this hybrid asset class offers private-grade architectural standards, comprehensive clubhouse facilities, and gated security at an accessible initial entry price. Over decades of policy cycles, ECs have established a track record as a resilient wealth-building vehicle for eligible middle-income households, blending immediate homeownership utility with compelling long-term capital preservation fundamentals.
The Capital Appreciation Arc: The Privatisation Catalyst
The primary investment thesis behind the executive condominium model lies in its built-in legislative transition. Purchased under Housing & Development Board (HDB) guidelines, units are subject to regulatory milestones that dictate market liquidity and pricing power:
- Years 1 to 5 (The Minimum Occupation Period): Owners cannot rent out the entire unit or dispose of the property, which suppresses speculative flipping and creates an artificial period of capital consolidation.
- Years 6 to 10 (Semi-Privatised Phase): Upon completing the 5-year MOP, units can be traded on the open market to Singapore Citizens and Singapore Permanent Residents (PRs), unlocking secondary-market transaction volume.
- Year 11 Onward (Full Privatisation): The development sheds all remaining HDB restrictions, becoming fully accessible to international individual buyers and corporate entities. This step eliminates the traditional pricing gap relative to neighbouring private developments.
For forward-planning families assessing newer launches, this long-term appreciation trajectory forms a cornerstone of their financial planning. In enclaves such as Solano Grand, situated near mature transit nodes and nature belts in District 23, the inherent entry-price discount relative to surrounding fully private condominium benchmarks provides a significant safety margin against future cyclical market adjustments.
Structuring Financing and Mortgage Flexibility
Financing an EC requires careful navigation of the Mortgage Servicing Ratio (MSR) and the Total Debt Servicing Ratio (TDSR). Because EC purchases fall under MSR guidelines during initial developer sales, monthly debt servicing cannot exceed 30% of a borrower’s gross monthly income:
- MSR Enforcement at Launch: While the 30% ceiling restricts initial borrowing leverage, it forces healthy equity cushions, ensuring buyers enter the development with lower default risks.
- Refinancing Post-MOP: Once the asset reaches secondary market status, loan calculations transition strictly to the broader 55% TDSR framework, offering substantially wider refinancing terms and equity extraction options.
- CPF Housing Grants: First-time buyer applicants can qualify for substantial Central Provident Fund (CPF) housing grants, directly reducing initial cash outlays and lowering monthly mortgage burdens.
Location Anchors: Regional Growth Hubs and Master Plan Upgrades
A property asset’s real-world capital velocity depends heavily on urban planning catalysts. Evaluating potential projects against the Urban Redevelopment Authority (URA) Master Plan reveals how local infrastructure projects elevate long-term rental demand and capital values.
Investors and owner-occupiers frequently monitor regional transformation corridors that introduce new employment nodes. Within northern residential gateways, developments such as Wynwood Grand in Woodlands benefit directly from the evolution of the Woodlands Regional Centre and the Rapid Transit System (RTS) Link. As cross-border commercial clusters expand and professional talent migrates toward regional employment hubs, surrounding residential assets capture robust tenant demand and long-term liquidity.
Exit Strategies and Portfolio Decoupling
A well-executed EC purchase acts as an effective springboard into wider property investment. Upon clearing the 10-year privatisation mark, homeowners possess multiple options to unlock accrued paper gains:
- Right-Sizing with Cash Proceeds: Empty-nesters can liquidate privatised EC units at full market price to fund smaller retirement apartments while pocketing substantial cash reserves.
- Portfolio Decoupling: Couples who held the initial property under joint tenancy can restructure ownership upon full privatisation, freeing up one party’s borrowing capacity to acquire a pure investment property without incurring Additional Buyer’s Stamp Duty (ABSD).
- High-Yield Rental Transition: A fully privatised asset in an established growth district offers stable rental yields, drawing expatriate professionals and local families seeking full condominium amenities.
By pairing government-backed entry advantages with structural capital appreciation at privatisation, executive condominiums remain one of the most reliable vehicles for middle-tier households seeking to build durable, generational wealth.